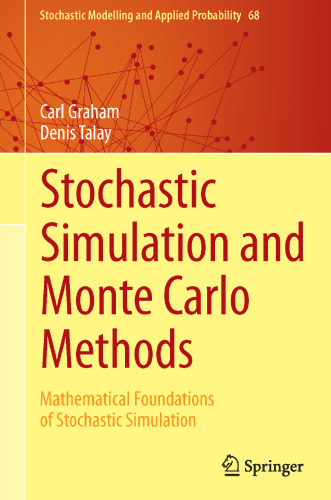
خرید و دانلود نسخه کامل کتاب Stochastic Simulation and Monte Carlo Methods: Mathematical Foundations of Stochastic Simulation
شبیه سازی تصادفی و روش های مونت کارلو: مبانی ریاضی شبیه سازی تصادفی
Stochastic Simulation and Monte Carlo Methods: Mathematical Foundations of Stochastic Simulation
نویسنده: Carl Graham, Denis Talay (auth.)
ناشر: Springer-Verlag Berlin Heidelberg
سال انتشار: 2013
تعداد صفحات: 264
زبان: English
فرمت: pdf - قابل تبدیل به سایر فرمت ها
حجم فایل: 2 مگابایت
110,000 تومان
78,000 تومان